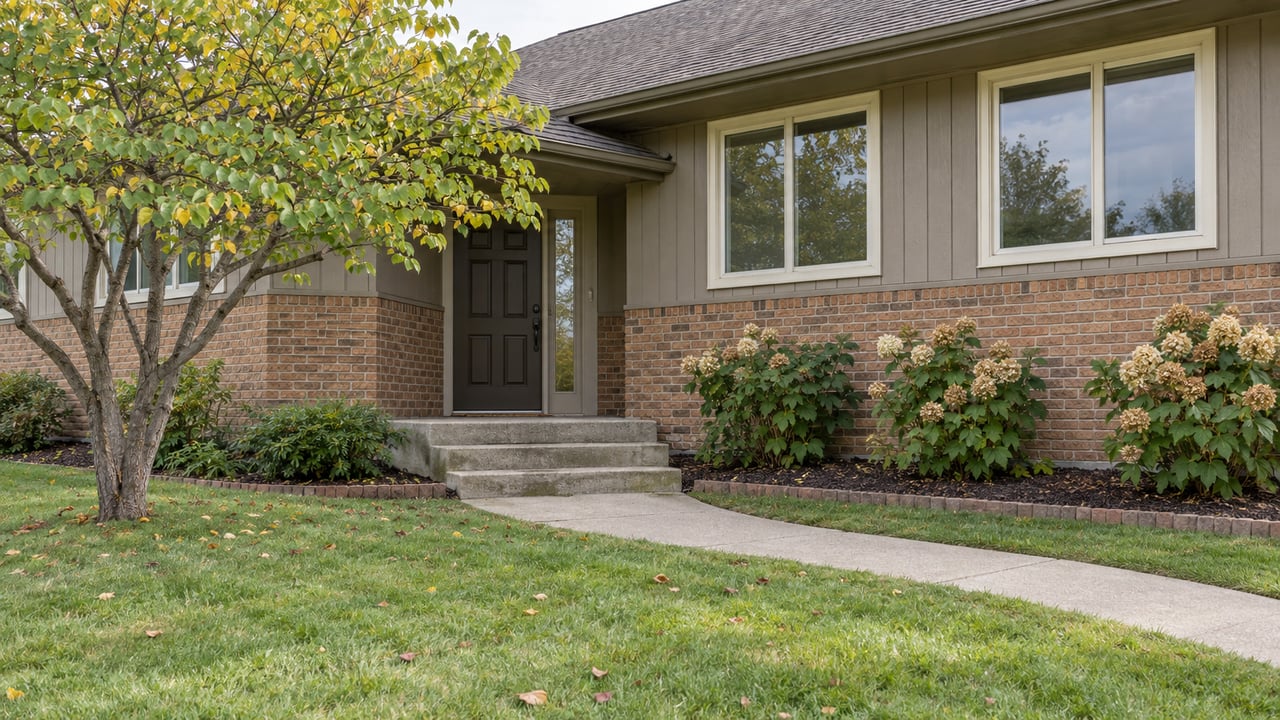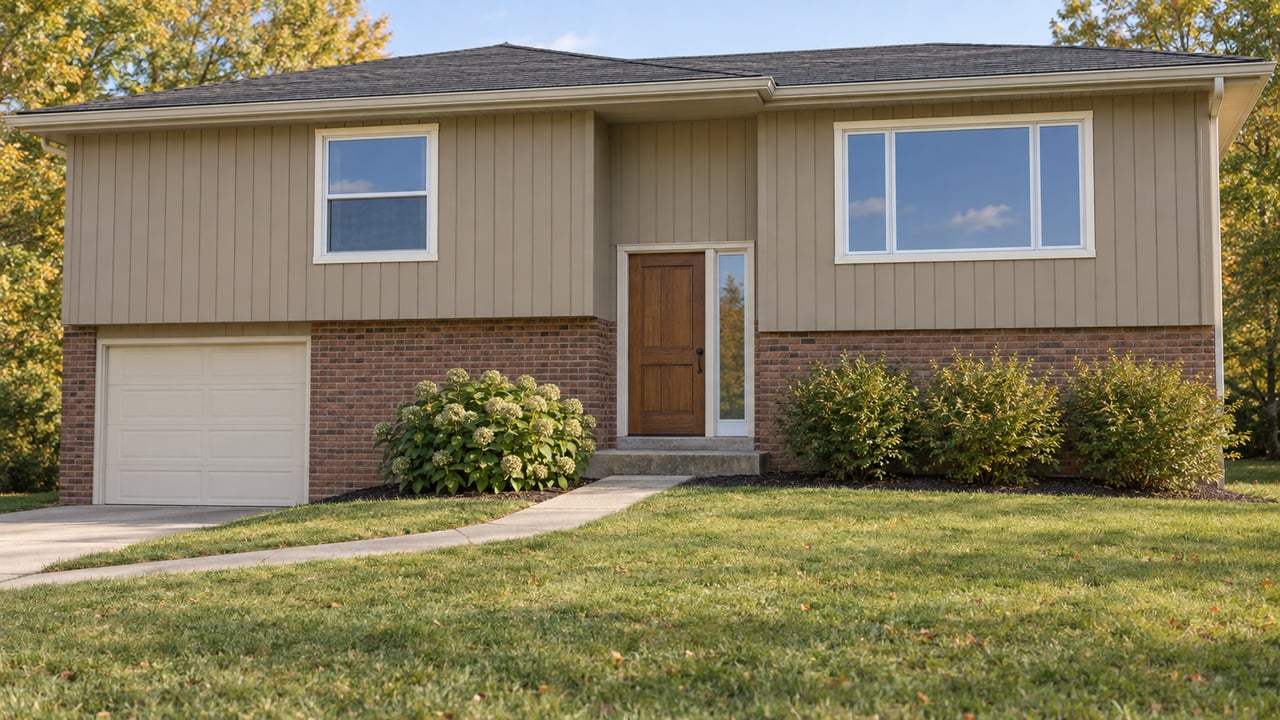
A five bedroom home in Riss Lake may involve a conventional loan officer who can quote a rate in about ten minutes. A new estate home in The Sanctuary at Riss Lake may instead involve reserve documentation, a second appraisal, and a down payment several times larger as a share of the purchase price. Both homes are in the same subdivision, under the same homeowners association name, a few minutes apart by car.
The financing distinction is not about school assignment, lot grading, or how the kitchens were finished. It comes down to a single number: $832,750, which is Missouri's conforming loan limit for a single unit home in 2026. A loan amount above that figure is a jumbo loan, and the financing conversation changes.
The line itself
Every year the Federal Housing Finance Agency sets a ceiling on how large a mortgage Fannie Mae and Freddie Mac will buy from a lender. Missouri has no counties designated as high cost, so the baseline ceiling applies the same way in Platte County as it does everywhere else in the state. For 2026, that ceiling sits at $832,750 for a one unit property, according to Rocket Mortgage's breakdown of the year's limits. A loan a dollar above that figure is, by definition, a jumbo loan rather than a conforming one, and it stops qualifying for the pricing and underwriting rules that apply to the vast majority of American mortgages.
In most of the Northland, this line is close to irrelevant. A typical entry to mid market home in Parkville, Gladstone, or Riverside sells well below it, and buyers rarely think about the conforming ceiling at all. Riss Lake is the exception.
Riss Lake asking prices approach the loan limit
Listing data from this year puts Riss Lake's median asking price somewhere between $725,000 in the summer and $800,000 in the spring, depending on which snapshot you pull and which section of the neighborhood happens to be listed that month. The broader range runs from around $600,000 for older, off water homes up to well over $2,000,000 for waterfront estates. A handful of active listings this spring told the same story at a smaller scale: a five bedroom home on Gresham Circle listed at $599,900, a three bedroom on Vista Circle at $799,000, a five bedroom on Parkview Drive at $799,900, a four bedroom on Sleepy Hollow Drive at $725,000.
Notice where those numbers land. They are not clustered near the median home price for the Kansas City metro. They are clustered within striking distance of the exact figure that separates a conforming mortgage from a jumbo one. A buyer negotiating up from $799,900 by even a modest amount, or a seller agreeing to a concession, may change the financing needed, but whether the loan is conforming or jumbo depends on the loan amount, not the sale price alone.
That is the part that makes Riss Lake different from the rest of the Northland's housing stock. In neighborhoods where homes trade in the $250,000 to $400,000 range, the conforming ceiling is so far away that it never enters the conversation. In Riss Lake, those decisions can affect how much a buyer needs to borrow, bringing some loan amounts close to a federal lending threshold most buyers have never heard of.
The Sanctuary's loan amounts may cross the line
If the older, resale side of Riss Lake sits close to the line, the newest section of the neighborhood clears it without question. The Sanctuary at Riss Lake is a new community from Don Julian Builders set on two cul-de-sacs with 19 single family estate lots, all sized to accommodate four car garages, sitting adjacent to the Parkville Nature Sanctuary. Pricing there was projected to start at $1.3 million including the lot, and current construction reflects that tier. A five bedroom home under construction on Lentz Drive, the Brookridge IV plan at 3,694 square feet, is priced at $1,675,000.
A buyer borrowing more than $832,750 for a home in The Sanctuary has a jumbo loan, so the underwriting conversation can start there rather than arriving as a surprise mid transaction. Interestingly, the association fees for that section are structured differently too, with dues reported at $122 a month covering ground maintenance and snow removal, a separate figure broadly comparable to the roughly $1,390 to $1,460 a year that owners in Riss Lake's older sections pay for the broader package of pools, marina access, and common area upkeep. Same neighborhood name, same HOA governance structure in spirit, but a genuinely different product with its own cost profile from the ground up.
What actually changes when a loan amount crosses $832,750
The difference between a conforming and a jumbo file is not just a bigger number on the loan application. Several parts of the process shift at once.
| Conforming (up to $832,750) | Jumbo (above $832,750) | |
|---|---|---|
| Down payment | Often as low as 3 to 5 percent | Commonly 10 to 20 percent, sometimes more on larger balances |
| Cash reserves after closing | Typically not required beyond standard underwriting | Often 6 to 12 months of payments, more above roughly $1.5 million |
| Credit score | Often a 620 to 640 minimum | Commonly 700 or higher, with the best pricing closer to 740 |
| Appraisal process | Usually a single appraisal | Sometimes a second appraisal or desk review, adding time to closing |
That last row matters as much as the down payment does. Once a loan moves into larger jumbo territory, some lenders order a second, independent appraisal rather than relying on one. Scheduling two appraisers instead of one can add five to ten business days to a closing timeline, which is worth knowing before a contract locks in a tight closing date.
Why the comps get harder to find
There is a second, quieter problem that shows up specifically because Riss Lake contains both the older resale stock and The Sanctuary under one neighborhood name. An appraiser working a contract priced in the mid $800,000s is supposed to find three recent comparable sales nearby. In most neighborhoods, that pool is straightforward. In Riss Lake, it splits. The nearby comps within reach of that price point are either aging resale homes from the 1990s and early 2000s selling in the $600,000s and $700,000s, or brand new estate homes in The Sanctuary opening at $1.3 million and up. Neither group looks much like a home selling near $832,750, which can make it harder to support the appraised value and lead to a renegotiation.
This is not a reason to avoid the neighborhood. It is a reason to expect the appraisal step to take more explanation than it would elsewhere, and to have a pricing strategy and a set of supporting comps ready before the appraiser arrives rather than after a number comes back lower than expected.
What to do with this if you are buying or selling near the line
If you are selling a Riss Lake home priced anywhere from the high $700,000s into the $800,000s, it is worth having a conversation with your agent about how a buyer's financing structure interacts with your asking price before you accept an offer. A seller concession or a slightly higher accepted offer may affect the amount a buyer needs to finance; the loan amount, not the sale price alone, determines whether the loan is conforming or jumbo.
If you are buying, the more useful move is to ask your lender exactly where your specific loan amount falls relative to $832,750 before you get emotionally attached to a number on a listing. A price that looks like a stretch by $15,000 might actually be the difference between a straightforward underwriting path and a longer one with more paperwork.
Does a jumbo loan always mean a higher interest rate? Not necessarily. Rate spreads between conforming and jumbo loans have narrowed considerably, and well qualified borrowers with strong credit and healthy reserves sometimes see jumbo pricing that matches or beats conforming rates. The rate itself is often less of an issue than the reserve requirements and appraisal timeline.
What if my Riss Lake home appraises for more than the contract price? That works in the buyer's favor for equity but does not change which loan program applies. The loan amount, not the appraised value, determines whether a file is conforming or jumbo, so a buyer financing $820,000 on a home that appraises at $860,000 is still working within conforming limits.
Financing thresholds like this one rarely show up on a listing sheet, but they shape how a Riss Lake deal actually comes together from the first offer to the closing table. If you are weighing a purchase or a sale in Riss Lake and want to talk through how your specific price point lines up against this year's lending rules, Northstar Realty is happy to walk through it with you before you write or accept an offer.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.